Thursday October 22, 2026
Water risk in high-rise buildings: Expert insights from Andrew Lester
 For board and strata council members of high-rise buildings, protecting property value increasingly comes down to three connected disciplines: reducing or minimizing water risk before it becomes a claim, understanding how that risk shows up in insurance pricing, and having a realistic way to pay for the systems that mitigate losses in the first place. Taken together, they give boards a proactive financial strategy for loss prevention, not just a maintenance checklist.
We sat down with Andrew Lester, president of FirstService Financial, to discuss how boards can align water risk mitigation, insurance strategy, and financing to better protect their communities.
Q: Where should boards start when it comes to reducing property loss risk?
"Water. Escape of water is the most frequent claim a high-rise will face, and it's usually the most expensive, so it's where a board gets the most protection for the least effort.
Getting ahead of it means two things: better detection on the building's own systems, and clear accountability for what happens inside individual units, since a surprising share of losses start there.
What makes water the right starting point is that boards can significantly reduce losses by investing in proactive measures. A board can't dictate the weather or where the insurance market goes, but it can decide how well its building is monitored, how quickly a leak gets caught, and how clearly residents understand their role.
That's the heart of good risk management: focusing on what you can help prevent and building the habits and systems that keep small problems from becoming major losses."
Andrew Lester, president of FirstService Financial
Q: What technologies can help prevent losses before they start?
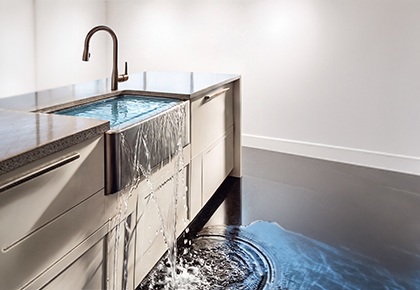
"The numbers really tell the story here. An internal review of more than 10 years of claims data from over 1,000 condos found that about 51% of property claims are water related, with more than half considered preventable, primarily at the unit-owner level. So that's where we should look first: inside the units.
That's where most of these losses quietly begin. It's the dishwasher, the washing machine hose, the aging in-unit water heater, the air conditioning unit with a clogged condensate line that drips through a ceiling for days before anyone realizes it.
The most effective tool is a simple one: leak detection sensors at those trouble spots, backed up at the building's own weak points like mechanical rooms, plumbing risers, and amenity spaces. Sensors buy you time, and the best systems go a step further by adding automatic shutoff valves that close the line the second a leak shows up.
That way the damage stops itself, even if the unit is empty or the owner is traveling. It's also worth tracking humidity data in common areas, because a steady rise in moisture often shows up before an actual leak does. Over time that data helps the team get more intuitive about where and when problems are likely to surface, so you're anticipating them instead of just reacting.
Keep in mind that different leak detection sensor systems work differently; board and strata council members, and their management teams, should consult a professional to determine which system is right for them.
The real value is that it works two ways at once. You stop the loss in the moment, and over time you file fewer and smaller claims, which is exactly the history a carrier rewards when it comes time to price and renew your policy."
Q: Once a board decides to invest in systems like these, how do they typically fund it, especially without full reserves?
"This is where they often get stuck. They understand the value of water detection or envelope repairs, but they don't have the reserves to pay cash, and financing capital projects can feel intimidating or out of reach.
That's exactly the gap our lending team exists to close. We don't just identify a bank they can work with. We manage the entire process ourselves: analysis, underwriting, negotiation, documentation, closing, and funding.
Because we work exclusively with high-rise and community associations and have relationships across more than 20 lending partners, we can negotiate pricing and terms a high-rise typically can't get on its own, often at a meaningfully lower interest cost and with a much faster closing timeline than applying directly.
The bigger point is that financing shouldn't be viewed only as a last resort after a loss. Used proactively, it's a way to fund the very capital projects, detection systems, and envelope work that reduce claims and strengthen a building's standing with its insurer. Prevention, insurance, and financing aren't three separate conversations. They reinforce each other."
Q: How are insurance carriers viewing risk mitigation today?
"Carriers are looking closely at whether a building is actively managing its risk, not just what it looks like on paper. A board and strata council that can document a history of capital improvements, structural upgrades, safety technology, and current inspections is generally viewed more favorably.
That kind of documentation strengthens underwriting conversations and may open up broader coverage options or more competitive premiums. The tighter the connection between maintenance, capital planning, and insurance strategy, the better positioned a building is when its coverage is reviewed or a claim occurs.
It's also the part of the equation that can be controlled the most. No one can impact where the broader insurance market goes, but every board can impact its own loss history."
Q: How much of loss prevention depends on residents, and what can boards and strata councils do about it?
"More than they may think. The sensors and shutoffs we talked about do a lot of the work, but hardware only goes so far if the person living in the unit isn't part of the plan. Many of the biggest losses trace back to something an owner controlled: a water heater nobody replaced, a supply line nobody checked, an appliance left running.
The good news is that this is where a board actually has leverage, and most of it costs very little. You can set a maximum age on in-unit water heaters and require proof they're being replaced as needed. You can make leak sensors a condition rather than a suggestion. You can require owners to carry adequate unit-owner insurance, which takes a lot of the friction out of the relationship between owners and the board, because responsibilities are clear before anything goes wrong rather than being addressed afterward.
And you can invest in educating owners more broadly, not just on water, but on the full range of insurance and risk management issues that affect the building, so residents understand how their choices tie back to coverage, cost, and the health of the association as a whole.
The real shift is cultural. When residents see themselves as partners in protecting the building, not just people who file a claim after something breaks, prevention stops being the board's job alone and becomes everyone's. That shared ownership is what keeps small problems small, and it protects the value of every unit in the building."
"Prevention, insurance, and financing aren't three separate conversations. They reinforce each other."To learn more about how FirstService Residential can support your community, contact a member of our team.
Andrew Lester, president of FirstService Financial
Contact us to learn more about how FS Insurance Brokers, a subsidiary of FirstService Financial, can support your building’s financial well-being through proactive water detection solutions.
This information is provided for general informational purposes only and is not intended to constitute, and should not be relied upon as, legal, regulatory, financial, or operational advice, or as a representation or guarantee of any specific services, capabilities, or outcomes. Property management needs, regulatory requirements, market conditions, and available services vary by jurisdiction, property type, and community. FirstService Residential provides services through locally based affiliates and associates, and services and results may vary by community, region, contractual terms, and applicable law.
To review additional information about FirstService Financial's services and disclosures, you may access our Transparency Brochure.